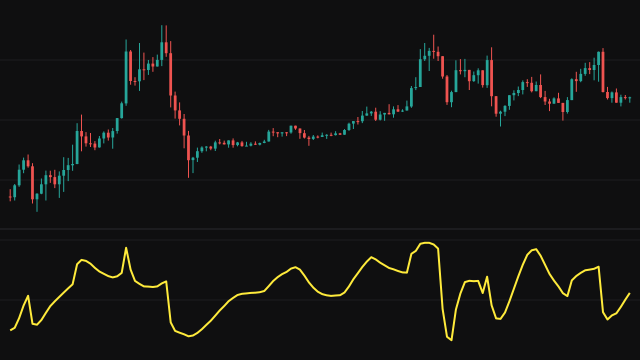
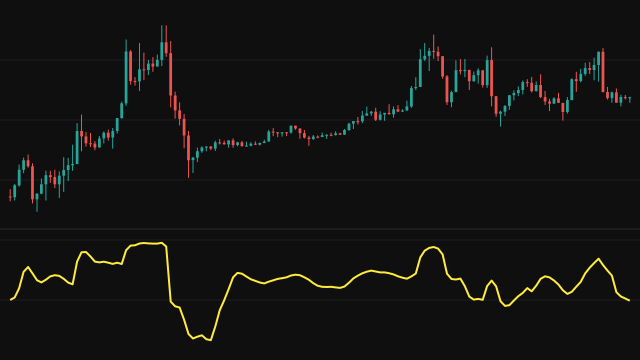
Smoothed Adaptive Momentum measures the change in the close over a lookback that is not fixed. The study first estimates the dominant cycle of the market and then takes momentum over one cycle: the close now minus the close that many bars back.
The cycle estimate runs in stages. The close is smoothed with a four-bar weighted average, a detrender and a quadrature filter split it into two components, both are advanced by a quarter turn, and the products of the results are averaged with the weight alpha. The phase angle between them gives a cycle period, held between 6 and 50 bars and then smoothed twice from a start of zero; the lookback is that smoothed period rounded down, at least 1 bar, so it climbs from 1 over the first bars and stays below 50. The momentum is then passed through a two-pole smoothing filter whose cutoff is cutoff bars. Every read of a bar before the start of the chart counts as zero, so the line starts on the first bar.
The cycle estimate depends on the price level. The detrender multiplies by a factor that grows with its own previous value, so on an instrument priced in the tens of thousands its stages grow without limit and run past the largest number the engine holds. Each such value counts as zero on the next bar, the period falls to its 6-bar floor, and the smoothed period settles just under 6, so the lookback is 5 bars for most of the chart. On the same bars scaled to lower prices the lookback instead sat at 49 bars, at 6, or moved between 27 and 49, so the lookback is not a reliable measure of the market's cycle.
How to read SAM: Smoothed Adaptive Momentum
Above zero, the close is higher than it was one measured cycle ago; below zero, lower. The smoothing filter removes most of the bar-to-bar noise, so a turn in the line reflects a change in the direction of the move over the last cycle. A crossing of the zero line marks the close moving back through its level of one cycle earlier.
The reading is in price units, so its size scales with the instrument's price. The first bars are distorted because the earlier bars are counted as zero, so read the line only once it has settled.
Settings
- alpha
- The weight used to average the cycle components. Smaller values make the cycle estimate steadier and slower to change.
- Cutoff
- The cutoff period in bars of the two-pole filter applied to the momentum. Larger values give a smoother, slower line.
Frequently asked questions
What lookback does the momentum use?
The twice-smoothed cycle period, rounded down to whole bars, at least 1 and below 50. On a high-priced instrument the cycle stages overflow, the period sits at its 6-bar floor and the lookback is 5 bars; at other price levels it can sit at 49 bars or move between the two.
Why does the line start with a large swing?
Bars before the start of the chart are counted as zero, so the first momentum values compare the close with zero. The filter carries that start for a few bars before the line settles.
Can I change the source?
No. The study always measures the close.